

If you’ve ever stared up at a damaged roof after a storm, you’ve probably asked the big question: is roof repair covered by home insurance? It’s one of the most common questions we hear at Done Right Roof And Gutters here in Magnolia — and the answer (like most insurance answers) is “it depends.” Coverage hinges on what caused the damage, how old your roof is, and the fine print in your policy.
We’ve helped homeowners across Magnolia, Tomball, The Woodlands, and beyond navigate this exact situation. So in this 2026 guide, we’ll break down when your insurance pays, when it doesn’t, and how to give yourself the best shot at a successful claim. Let’s dig in.
When Does Home Insurance Cover Roof Repair?
Most standard homeowners insurance policies cover roof repair when the damage is caused by a sudden, accidental event — what insurers call a “covered peril.” Think storms, falling trees, fire. The key word is SUDDEN. Insurance is designed to protect you from surprises, not from slow wear and tear that happens over years.
Here in Texas, we see plenty of wind and hail damage — and the good news is that most policies treat those as covered events. If your roof took a beating during a storm, there’s a solid chance your insurer will help foot the bill. If your roof damage also affected your gutters, you may want to look into our professional gutter repair services to handle the full scope of the work.
Common situations where home insurance typically covers roof repair include:
- Wind damage — shingles torn off or lifted during high winds
- Hail damage — dents, cracks, or bruising from a hailstorm
- Falling objects — a tree limb or debris crashing onto your roof
- Fire or smoke damage — structural harm caused by fire
- Weight of ice or snow — less common in our area, but still covered
- Vandalism — intentional damage caused by someone else
- Sudden water damage — leaks resulting from a covered peril
What Roof Damage Is Not Covered by Home Insurance?
Here’s where a lot of homeowners get tripped up. Insurance is NOT a maintenance plan. If your roof fails because it simply got old or because you skipped routine upkeep, your insurer will likely deny the claim. They expect you to maintain your home — and that includes keeping your roof and gutters in good shape.
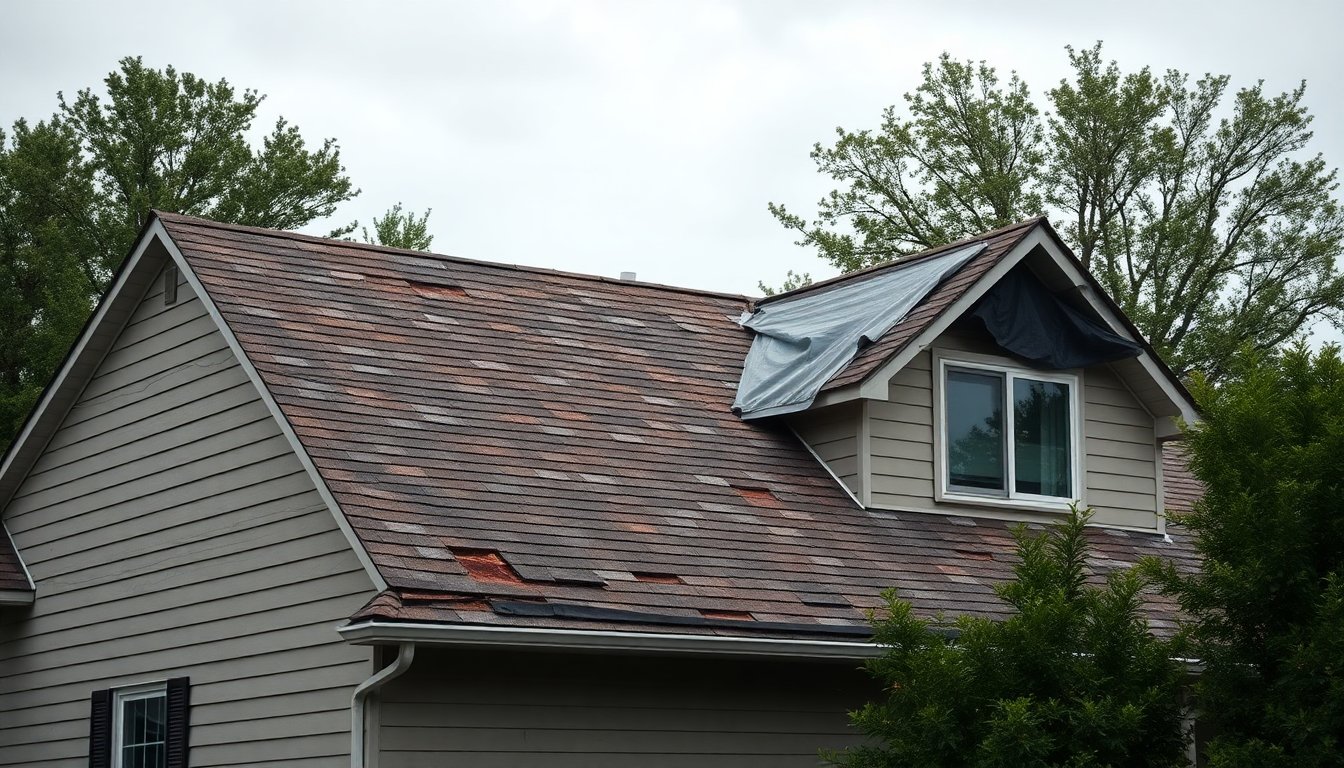
We always tell our customers in Spring, Cypress, and Pinehurst: a little prevention goes a long way. Many denied claims could’ve been avoided with regular maintenance. You can learn more about the full range of roofing and gutter services we offer to keep your home protected year-round.
Damage that’s usually NOT covered includes:
- Normal wear and tear — aging shingles, gradual deterioration
- Neglect or lack of maintenance — moss buildup, clogged gutters causing rot
- Pest damage — birds, squirrels, or insects chewing through materials
- Improper installation — work done by an unlicensed or careless contractor
- Pre-existing damage — issues that existed before your policy started
- Cosmetic damage — some policies exclude purely aesthetic issues
- Manufacturer defects — these fall under product warranties, not insurance
How Does Roof Age Affect Insurance Coverage?
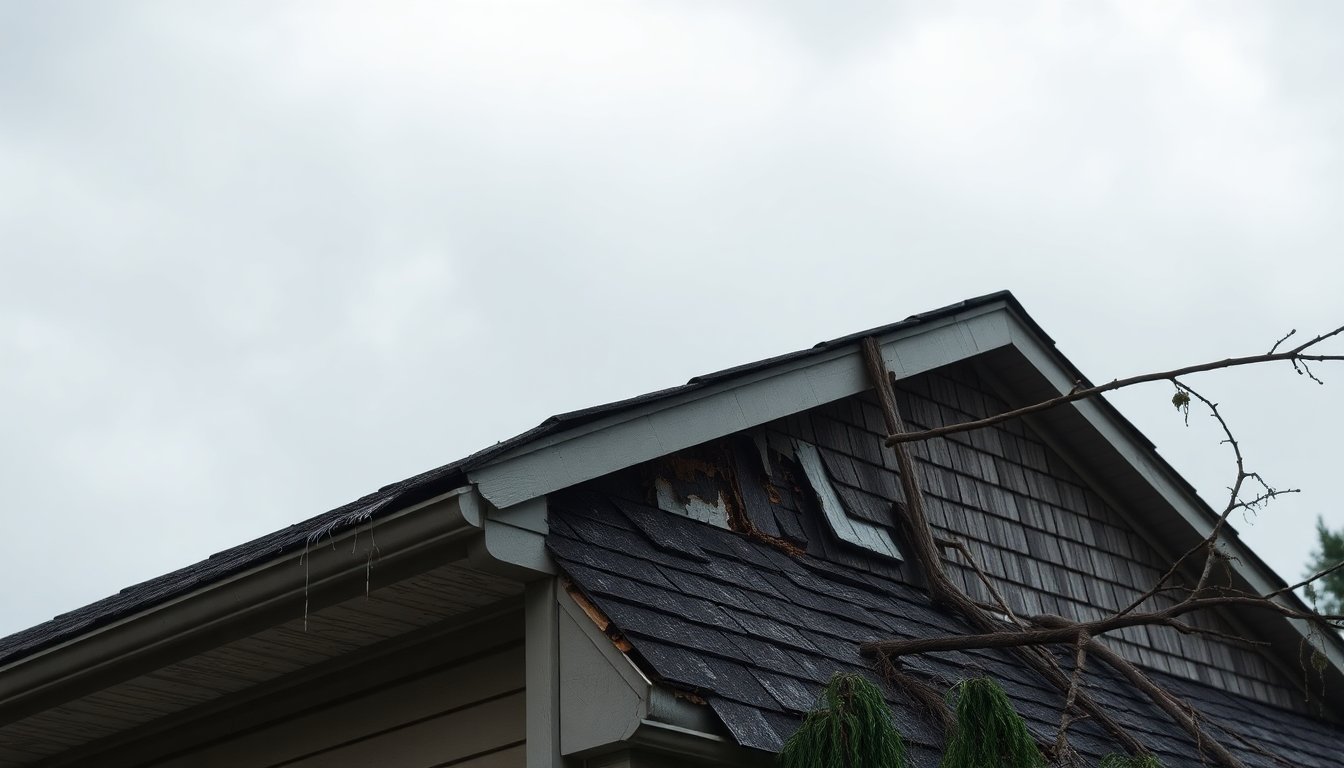
Roof age is a HUGE factor — and it surprises a lot of homeowners. The older your roof, the harder insurers get about coverage. Some companies reduce your payout as the roof ages, and others may refuse to cover certain roofs entirely. Let’s break down how age plays into the equation.
Roofs Under 10 Years Old
Newer roofs get the best treatment. If your roof is under a decade old and properly maintained, most insurers will provide full replacement cost coverage. That means they pay to repair or replace your roof at today’s prices — no deductions for age.
Roofs 10 to 20 Years Old
Once your roof passes the 10-year mark, things change. Many insurers switch to actual cash value (ACV) coverage. This accounts for depreciation, so your payout will be lower than the full cost of replacement. The older the roof, the bigger the deduction.
Roofs Over 20 Years Old
This is the danger zone. Some insurers won’t cover roofs older than 20 years at all — or they’ll only offer ACV with steep depreciation. Others may require an inspection before renewing your policy. If your roof is in this range, it might be time to consider replacement BEFORE you have a problem.
Why Insurers Care So Much About Age
It comes down to risk. Older roofs are more likely to leak, fail, and cause expensive water damage. Insurers price that risk into your policy. Keeping documentation of your roof’s age, condition, and any repairs can help you fight for fair coverage.
How to File a Roof Damage Insurance Claim
Filing a claim doesn’t have to be overwhelming — but doing it the RIGHT way matters. A sloppy claim can get denied or underpaid. Follow these steps to give yourself the best possible outcome after roof damage in Magnolia, Montgomery, or anywhere we serve.
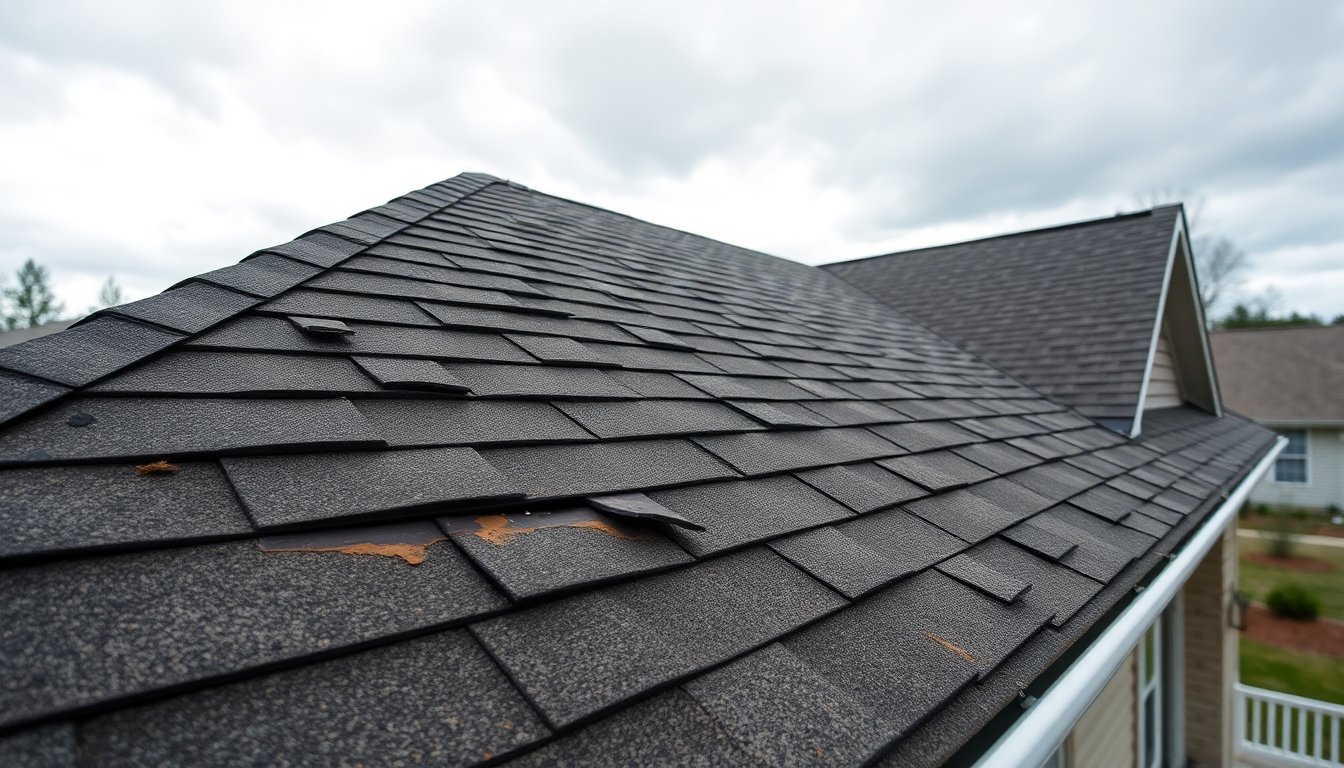
- Document the damage immediately. Take clear photos and videos from multiple angles. Note the date and what caused the damage.
- Prevent further damage. Cover leaks with a tarp if you can do so safely. Insurers expect you to limit additional damage.
- Review your policy. Check your coverage type, deductible, and any roof-specific clauses before you call.
- Contact your insurance company. File the claim promptly — many policies have time limits for reporting damage.
- Get a professional inspection. Have a licensed roofer assess the damage and provide a written estimate. This strengthens your claim.
- Meet the adjuster. When the insurance adjuster visits, having your roofer present can help ensure nothing gets overlooked.
- Keep all records. Save every email, estimate, photo, and receipt related to your claim.
- Schedule the repair. Once approved, hire a trusted contractor to complete the work properly.
If you need a reliable team to inspect your roof or work alongside your adjuster, our crew is happy to help — you can reach out to schedule an inspection and get started.
How Much Does Roof Repair Cost With and Without Insurance?
Costs vary widely depending on the damage, materials, and size of your roof. But the difference between paying out of pocket and using insurance can be DRAMATIC. With insurance, you typically only pay your deductible (often $1,000 to $2,500) — the rest is covered. Without insurance, you’re on the hook for the full amount.
Here’s a rough breakdown of common roof repair scenarios and what you might expect:
| Type of Repair | Cost Without Insurance | Typical Cost With Insurance (Deductible) |
|---|---|---|
| Minor leak repair | $300 – $1,000 | Often below deductible — out of pocket |
| Shingle replacement (small area) | $500 – $1,500 | May be below or near deductible |
| Storm/wind damage repair | $1,500 – $4,500 | $1,000 – $2,500 (deductible only) |
| Hail damage repair | $2,000 – $6,000 | $1,000 – $2,500 (deductible only) |
| Major structural repair | $5,000 – $12,000+ | $1,000 – $2,500 (deductible only) |
| Full roof replacement | $8,000 – $25,000+ | $1,000 – $2,500 (if covered) |
As you can see, insurance can save you thousands on bigger jobs — but for small repairs that fall below your deductible, you’ll likely pay out of pocket. That’s why it doesn’t always make sense to file a claim for minor work.
What to Do If Your Roof Repair Claim Is Denied
A denied claim feels like a gut punch — but it’s NOT the end of the road. Insurers deny claims for all kinds of reasons, and many denials get overturned on appeal. The trick is to stay organized, understand WHY you were denied, and respond with solid evidence.
Here’s what to do if your roof repair claim gets denied:
- Read the denial letter carefully. Insurers must explain why they denied your claim. Understand the specific reason.
- Review your policy again. Make sure the denial actually lines up with your coverage terms — mistakes happen.
- Gather more evidence. Additional photos, weather reports, and inspection records can strengthen your case.
- Get a second opinion. A licensed roofer can provide an independent assessment that contradicts the insurer’s findings.
- Request a re-inspection. Sometimes a second adjuster sees things differently — politely ask for another look.
- File a written appeal. Submit a formal appeal with all your supporting documentation.
- Hire a public adjuster. For larger claims, an independent adjuster can advocate on your behalf.
- Contact your state insurance department. If you believe the denial was unfair, you can file a complaint.
Persistence pays off. We’ve seen plenty of homeowners get their claims approved on the second or third try simply by providing better documentation and a professional inspection report.
Conclusion
So — is roof repair covered by home insurance? The honest answer is that it depends on the CAUSE of the damage, the AGE of your roof, and the details of your policy. Sudden events like storms, hail, and falling trees are usually covered. Wear, tear, and neglect typically are not. And the older your roof gets, the more careful you’ll need to be about your coverage.
The best thing you can do is keep your roof and gutters well maintained, document everything, and work with a trusted professional when damage strikes. Here at Done Right Roof And Gutters, we proudly serve homeowners across Magnolia, Tomball, The Woodlands, Spring, Cypress, and the surrounding areas — and we’re always ready to help you inspect, repair, and protect your home. Reach out today and let’s make sure your roof is done RIGHT.


